Investment Mortgages: How KNBox Helps Banks Automate Property Ownership Evaluation
The Czech National Bank's new rules for investment mortgages place additional demands on banks when it comes to assessing property ownership. Yet determining how many residential properties an applicant actually owns is not always straightforward. KNBox offers a solution that uses a specialised algorithm to automate not only the retrieval of data from the Real Estate Cadastre, but above all its evaluation against defined rules.
Investment mortgages and the new CNB rules
In November 2025, the Czech National Bank (CNB) issued a recommendation that, from 1 April 2026, tightens the conditions for mortgage lending to finance residential property bought as an investment.
For these loans, the CNB recommends applying two key limits:
- LTV of no more than 70% – the ratio of the mortgage loan amount to the value of the pledged property.
- DTI of no more than 7 – the ratio of the applicant's total debt to their net annual income.
The stricter limits apply not only when residential property is purchased as an investment, but also when financing a third or any subsequent residential property, regardless of the purpose of the purchase. While the investment purpose can be determined from the information in the mortgage application, establishing how many residential properties an applicant owns requires a reliable evaluation of their ownership. This is precisely the part of the process that KNBox helps automate.
What looks like a simple requirement at first glance, however, turns out to be a fairly complex process in practice.
Counting the properties isn't enough. What matters is evaluating them correctly.
Retrieving information from the Real Estate Cadastre does not, on its own, mean that a bank can determine unambiguously how many residential properties a given applicant owns. The evaluation depends on a whole range of conditions and specific ownership arrangements.
For example, it is necessary to distinguish whether the property is a flat, a family house, a recreational property or some other type of real estate. The size of the ownership share also plays an important role, as do community property of spouses and cases where a single property is recorded under several ownership entries.
The same property may appear in the cadastral data more than once, yet it should only be counted once in the final total.
If a bank were to evaluate this information manually, its staff would have to not only look up the relevant data, but also correctly apply the individual rules, take the ownership arrangements into account and remove any duplicates.
KNBox: from data retrieval to automated evaluation
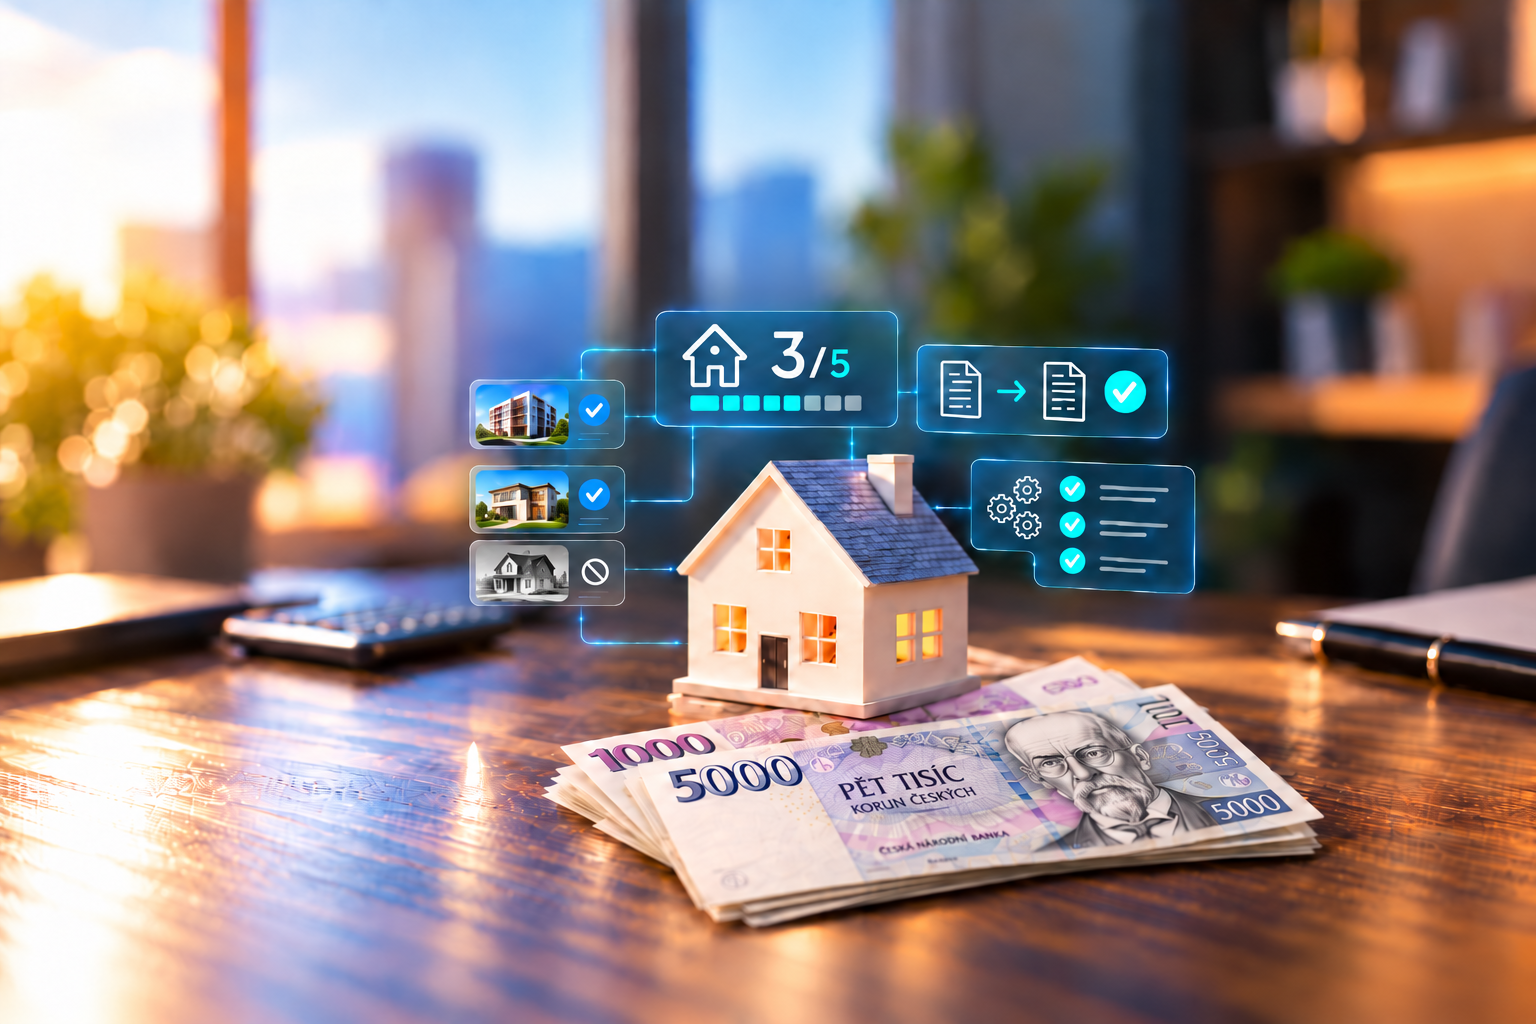
KNBox extends the ways banks can work with Real Estate Cadastre data by adding automated evaluation of residential property ownership, based on a methodology that reflects the CNB recommendation.
The solution's key added value lies not merely in automated data retrieval, but above all in a specialised algorithm that can apply complex evaluation rules without bank staff having to assess them manually.
During processing, KNBox automatically:
- Identifies owned properties – retrieves relevant information on the applicant's ownership from the Real Estate Cadastre.
- Distinguishes residential properties – uses the data recorded in the Real Estate Cadastre to identify the properties that are included in the automated evaluation under the defined methodology.
- Assesses ownership shares – applies the rules for counting properties, including the minimum ownership share threshold of 50%.
- Takes forms of ownership into account – handles both sole ownership and community property of spouses.
- Removes duplicates – ensures that the same property is not counted more than once for the same applicant.
- Evaluates multiple applicants – for joint applications, assesses each applicant's ownership and determines the decisive number of properties.
The result is a clear list of owned properties, including the total number of residential properties, evaluated according to uniform rules.
Bank staff can view the result directly in the KNBox user interface, or the same information can be passed via API to downstream banking systems and used within the existing mortgage application process.
Uniform rules, less manual evaluation
Automation brings banks several significant benefits.
Consistent evaluation based on a uniform methodology
The individual conditions and rules are applied by the KNBox algorithm, not by bank staff.
This reduces the risk of rules being interpreted differently, and the results stay consistent regardless of who processes a particular mortgage application.
Fewer manual tasks and a lower risk of error
In standard cases, bank staff no longer have to assess property types one by one, recalculate ownership shares or check for duplicate records.
These tasks are taken over by the algorithm, which follows a predefined methodology.
Automation thus helps reduce both the administrative burden and the risk of human error in the evaluation.
Easy integration into banking processes
Evaluation results can be made available directly in KNBox or passed via API to other banking applications.
Banks can therefore build automated ownership evaluation into their existing processes, without staff having to switch between systems and transfer their findings manually.
Automation where possible. Individual assessment where necessary.
Not every situation can be evaluated unambiguously on the basis of information available in the Czech Real Estate Cadastre alone.
Examples include properties owned abroad, or specific cases involving land intended for future residential development or properties intended for recreational use.
These situations still require individual assessment by bank staff.
KNBox therefore does not replace the bank's expert decision-making. Instead, it automates those parts of the process for which clear rules and the necessary supporting data exist.
This allows bank staff to focus more on the specific cases that genuinely require their expert judgement.
KNBox as a tool for a more efficient mortgage process
KNBox makes it possible to turn a complex methodology for evaluating residential property ownership into an automated process that works with available Real Estate Cadastre data, applies uniform rules and provides the bank with clear results.
Banks thus gain not only support in meeting the new regulatory requirements, but above all a tool that reduces the need for manual evaluation and helps make mortgage application processing more efficient.
More case studies from real projects

Standard No. 17: a new step toward automated data exchange between banks and authorised bodies
Bank data without manual re-entry: how DocuFlow shortens the path to a credit decision
Nové technologie, nové možnosti: SNOW, DocuFlow, BINF a KNBox v praxi
What should we automate for you first?
A specialist and 30 minutes. We talk about your processes. Concrete output, no commitment.